AI Infrastructure Category Boundaries and the Vendor Land Grab
Vendors battle over AI infrastructure labels to shape which competitors buyers see as peers.
AI infrastructure category boundaries are being fought over through language as well as capital. For platform and deep-tech companies that do not fit an existing category, the move is to name the buyer’s unmet problem, frame the new way of solving it, and keep that definition consistent across the organization. Vendors that make their vocabulary the buyer’s default get to shape the comparison before competitors enter it.
Why the AI infrastructure race is really a fight over vocabulary
Data center acreage, power, cooling, and GPU clusters make the infrastructure race visible. Meta’s Indiana campus and Nebius’s growth abroad show where that race is taking place. These are substantial commitments. But construction is only the visible contest. A second race shapes what buyers call the capacity being built, which vendors they see as peers, and what they expect a full offering to include.
That second race is less visible because its output looks like ordinary description. A buyer asks for “GPU-native” infrastructure, and a competitive premise arrives disguised as a requirement. The vocabulary has already narrowed the field. Land and power constrain what a vendor can deliver, while category language shapes whether that delivery enters consideration at all. The deeper scarcity is a place in the buyer’s working vocabulary, where a vendor’s definition can become everyone else’s admission test.
How the stack gets divided into named layers — and why those divisions are not neutral
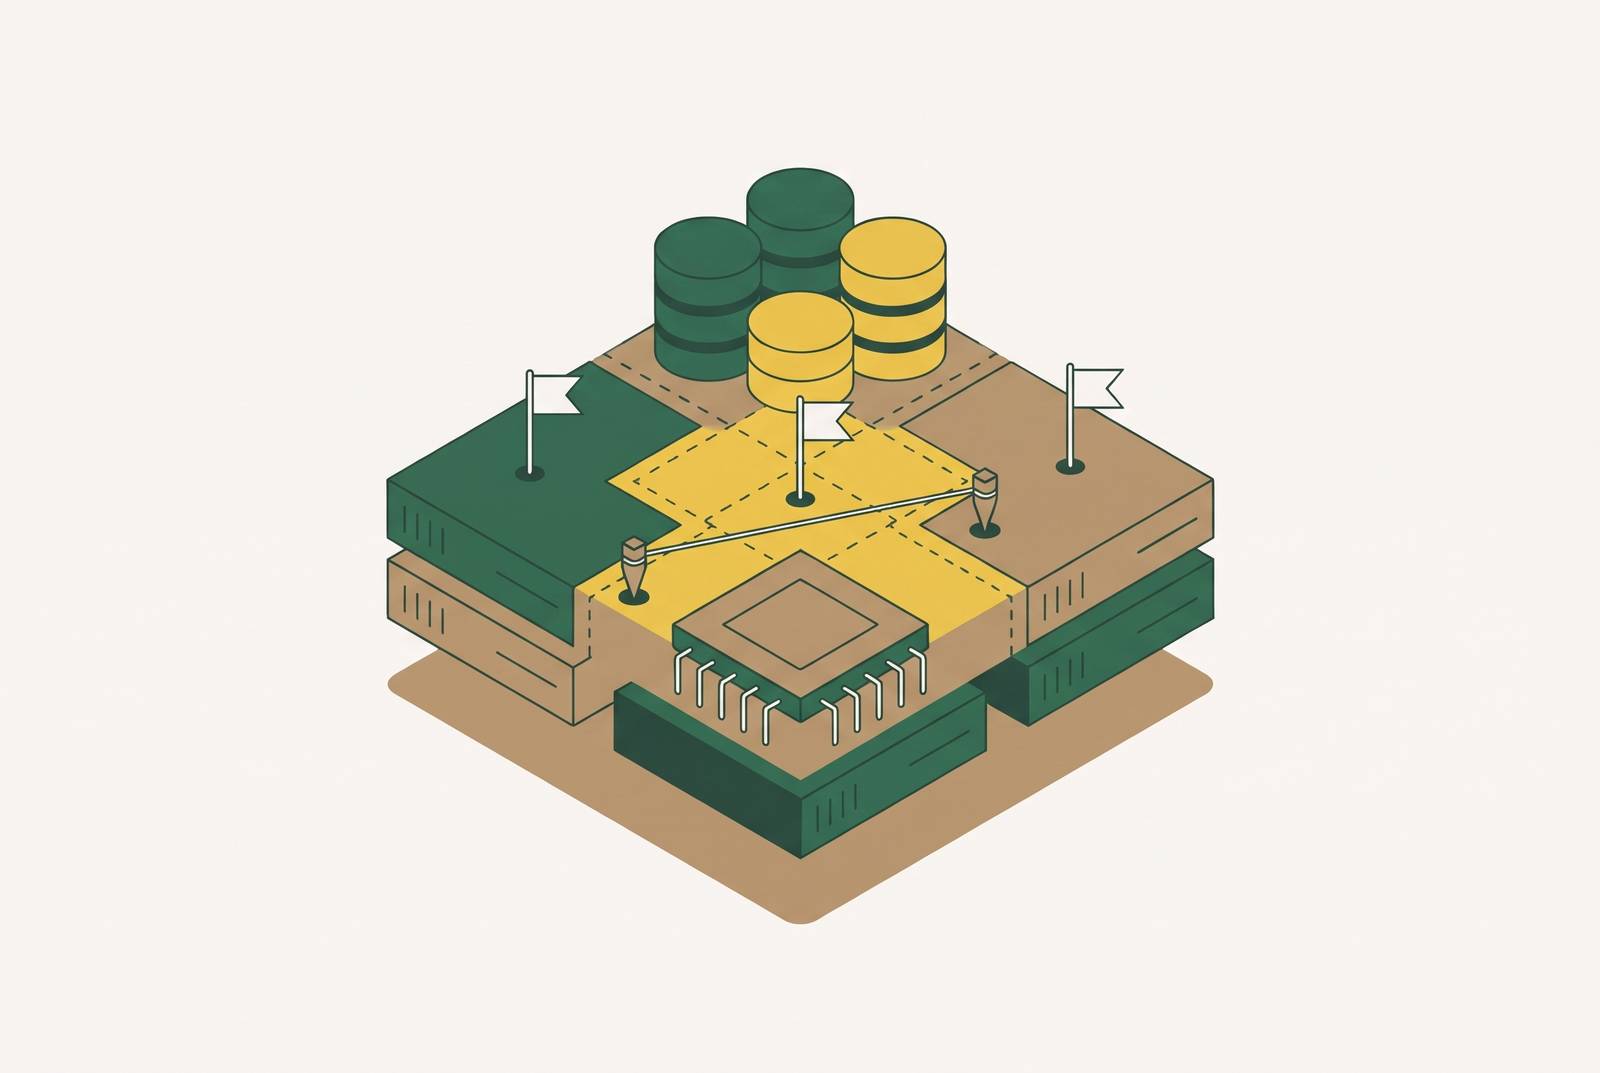
The commercial map drawn around technical dependencies is a proposal. A stack can be divided so that one vendor fits neatly into a named layer while another straddles several boundaries. That difference changes the comparison before performance enters it. “GPU-native” and “cloud-native” infrastructure overlap in compute, yet imply different procurement, pricing, and vendor lock-in logic. The map is not merely a diagram.
AI Infrastructure Acquisition Corp.’s SEC filing frames its scope through “artificial intelligence ("AI"), high-performance computing, cloud infrastructure, semiconductor acceleration (such as GPUs and specialized AI chips), edge computing, and the broader digital infrastructure value chain”. In a prospectus, those terms also mark the boundaries within which potential targets become legible as investments. A target must show where it fits on that map or explain why the map should stretch. The filing thus turns a choice of nouns into an evaluation grid for capital, with an inside, an outside, and some awkward positions on the fence.
How large capital commitments lock in not just infrastructure but the language around it
When a large commitment rests on a particular account of the market, that account gains a route out of the boardroom. Investors, partners, and buyers encounter the explanation attached to the money. Repetition gives it weight beyond the original transaction. The infrastructure becomes harder to reverse physically, while its justification becomes harder to displace intellectually.
NVIDIA’s part in OpenAI’s post-restructuring funding round shows how putting money into a company can tie their strategies together. The relationship gives rivals an alignment against which they may have to explain their own position, rather than leaving every vendor free to define the market from scratch. The consequence is a stronger reference frame, reinforced when buyers encounter similar investment narratives across large actors. At that point, the capital story can become the procurement story, and a strategic relationship starts doing work that no product specification could do alone.
Why physical geography is now entangled with narrative geography in this market
Location makes this coupling concrete because a site answers two questions at once. It says where capacity will sit and suggests what kind of infrastructure actor is building it. Meta’s Indiana campus sits within a story about how much land is available, how utilities work together, and what power costs. Those features make the case for building there. Labels such as “Silicon Prairie”, “emerging region”, and “utility-scale industrialization” turn that case into a pattern other investors can recognize, rather than a location they must explain from first principles.
Nebius’s expansion presents a different category signal. Its multi-billion-dollar deals with hyperscalers come as it expands across Europe, North America, and Asia-Pacific, putting specialized infrastructure in a global market. A label such as “regional AI infrastructure” can make local presence legible as a fundable capability, but it can also understate the scope of a globally expanding provider. The contrast is instructive, because Meta’s location helps frame an emerging hyperscale hub, while Nebius’s footprint challenges the assumption that specialized provision means limited reach.
How category labels form, drift, and get claimed in fast-moving technology markets
Technology categories usually take shape as people fight over what to call them, well beyond the naming ceremony. Vendors propose labels, buyers adopt or resist them, and analysts and capital allocators ratify the ones they find useful. The decisive step is adoption into buyer questions. Once a buyer asks for a category by name, competitors must explain their fit, their difference, or their reasons for rejecting the premise. Even rejection keeps the originating vocabulary in circulation.
Salesforce popularized “No Software” and “cloud CRM”, while HubSpot named “inbound marketing”. Gainsight popularized “customer success”, rather than inventing every practice that the term came to cover. These distinctions prevent category creation from becoming a fairy tale about whoever printed the first T-shirt. The labels helped people see markets in terms of shared problems and ways to solve them. Gong’s choice of “revenue intelligence” instead of “call recording software” makes the mechanism especially clear, moving the conversation from a feature comparison to a strategic initiative with a different executive budget owner.
However, creating a category is expensive and slow. It requires sustained coordination across strategy, narrative, and market education. Subcategory ownership offers a narrower alternative, defining a segment inside an existing category and becoming the obvious answer within it. That route saves the cost of teaching buyers the whole parent category and gives them more specific criteria to judge by. For a technology with no established search demand, the choice is therefore between teaching a new buying question and refining one buyers already ask.
What AI infrastructure vendors are actually doing when they name layers of the stack
AI infrastructure labels apply this mechanism to the boundaries of the stack itself. “GPU-native”, “agent-ready”, “energy-sovereign”, “photonic”, “hyperscale”, and “neocloud” each propose a way to group vendors and distinguish alternatives. These are bids to define the comparison. If buyers accept a label, they also begin accepting its assumptions about which capabilities belong together and which differences deserve attention. A category name is a small phrase with a surprisingly large procurement department.
CoreWeave’s framing of its proposed acquisition of Core Scientific treated power, cooling, land, and compute as a single integrated stack. The acquisition failed, but the framing remains an example of a structural category claim. It proposes ownership of the stack as the norm. The proposed frame’s competitive effect is that vendors that lease or partner for a layer can appear less complete regardless of their performance outcomes.
The SPAC filing makes a related move through hierarchy. Its phrase “semiconductor acceleration (such as GPUs and specialized AI chips)” makes GPUs the reference point and specialized chips the variant. Unmentioned approaches receive no explicit place in that description. The practical consequence is a cognitive default. Buyers who absorb either frame may evaluate a new entrant within it without noticing that someone chose the boundaries in the first place.
Why unclear internal language makes the external category fight unwinnable
A vendor cannot sustain a category claim externally when its teams cannot hold the definition internally. AI makes that weakness harder to contain. Large language models give confusion a distribution system by reproducing and distributing fragmented source vocabulary across generated outputs, turning local inconsistencies into an organization-wide liability.
Language debt is the accumulation of contradictory, undefined, or locally inconsistent terminology across an organization. Like technical debt, it makes downstream decisions harder and obscures the canonical version of a claim. A sales conversation, product document, and analyst briefing may each seem clear on its own yet place the company in different parts of the category. Sophisticated buyers have little time to reconcile them. In a short evaluation window, inconsistency can register as evidence that the company does not understand the role it claims.
That makes language debt an infrastructure problem. A claim to be the “agent-ready” layer must survive contact with the people and systems that take it to market. Agreement on adjectives is not enough. The underlying structural claim must remain stable across customer touchpoints, including AI-generated material. Otherwise, the company relies on a system that changes its category definition as it takes it to market, an awkward base from which to claim it can define anyone else’s market.
What governing organizational language actually requires at the scale AI infrastructure demands
Solving that problem requires narrative infrastructure, meaning language that is architected, versioned, maintained, and governed. A canonical document establishes the reference version of category claims, while a governance protocol determines how terms are proposed, adopted, and retired. AI tools need access to that canonical layer in place of inputs from across the organization that conflict with one another. The document’s authority depends on how the organization maintains it and uses it as the market changes.
Without that structure, a keynote term can become something different in a sales deck, product documentation, and an analyst briefing. Each team may think it has made the wording better. The buyer encounters four competing definitions instead. Generative tools sharpen the distinction because a polished pitch is now cheap to produce, while coherence under scrutiny remains demanding. A credible category claim must hold when an investor or buyer approaches it from different angles.
Storied has been building systems for how organizations use language since 2002. Its Narrative OS is designed as a protocol for managing language at scale, treating the canonical document as infrastructure. That makes it a practitioner option within this governing architecture. The relevant distinction is continuous language governance rather than periodic rebranding, with category definitions maintained as operating references. In this model, narrative is not the final coat of paint on strategy but part of the structure that lets strategy travel intact.
What AI infrastructure vendors should do now, before the category boundaries harden
For vendors, the immediate move is to define a layer through the buyer’s problem. The name must help buyers describe their need internally, including when no familiar category fits or analysts keep assigning the wrong one. Sales, product, investor relations, and AI tools need to hold the same claim so that market education does not unravel at the next touchpoint.
Kevin Maney and Mike Damphousse’s The Category Creation Formula expresses the logic as “Context + Missing + Innovation = New Market Category”. The category names a new way of doing things that needs to exist whether a particular vendor builds it or not. That is the useful test for a platform claim. It separates a buyer-relevant definition from a product description wearing a larger hat. Subcategory ownership remains an option when the unmet need fits within an existing frame and does not justify educating the whole market anew.
The timing is unusually important because AI infrastructure boundaries remain permeable. Dominant vocabulary hardens through analyst frameworks, investor prospectuses, and enterprise procurement templates, until a term in an RFP becomes a condition challengers must address. At that stage, the argument moves inside someone else’s definition. Capital can still build capacity, but it cannot by itself make buyers reconsider the question they have learned to ask. The window is open while that question is forming.