Platform vs Engagement Models for Portfolio Narrative Infrastructure in PE
A platform approach prevents narrative debt from compounding across portfolio companies and exits.
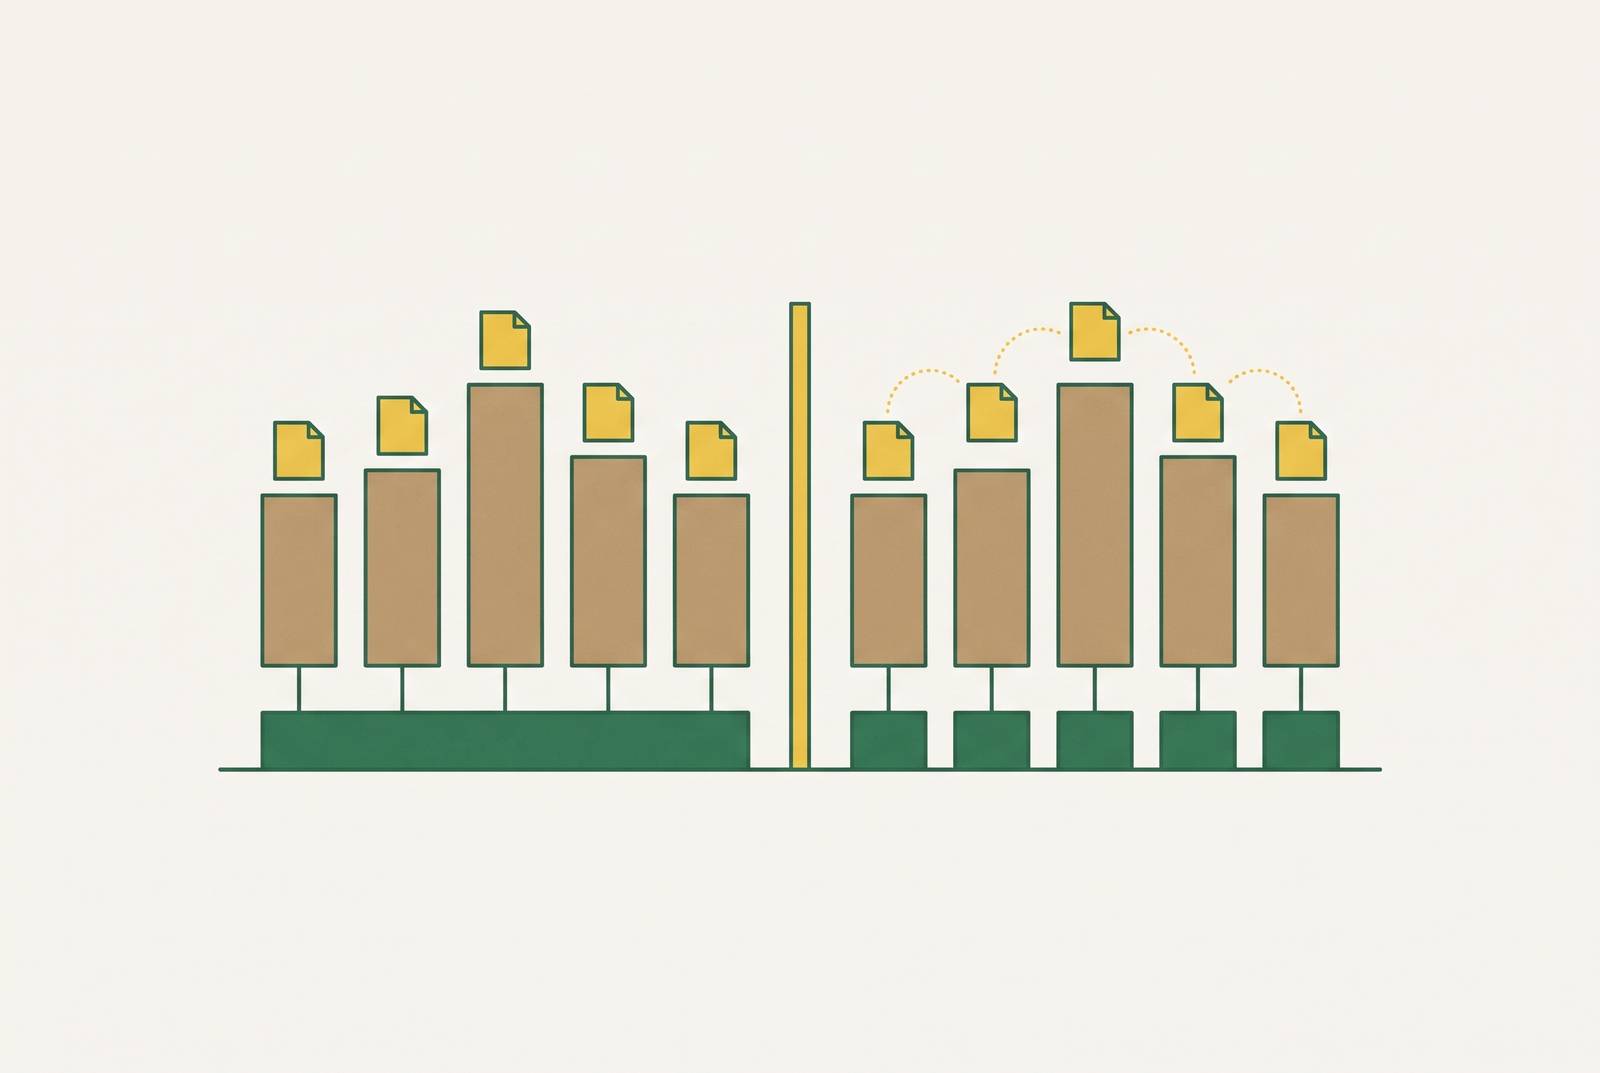
Portfolio narrative infrastructure in PE comes down to who owns the story between engagements. A fund-level platform provides shared language and ongoing governance, while discrete company engagements address individual needs without necessarily maintaining portfolio-wide coherence. A portfolio-wide narrative audit shows which approach fits by checking whether company stories tell the same story about the fund’s value-creation thesis. The wrong choice compounds narrative debt, leaving exit teams to reconstruct a story that should already be working.
Why PE value creation now depends on narrative coherence across a portfolio
Operational improvement, led by M&A and revenue growth, now does work that financial engineering once did. That puts more weight on whether operators, buyers, and capital providers understand how individual initiatives connect to the investment thesis. A growth plan needs more than a persuasive board presentation. It needs language that survives the journey into sales, hiring, product decisions, and management conversations. Otherwise, the plan and the business can start telling different stories.
AI adds another layer to that problem. FTI Consulting’s 2026 PE outlook expects portfolio companies to see AI-driven business model transformation and more complex AI orchestration. Both depend on clear organizational language to function at scale. When the source material contains competing accounts of the business, AI adoption raises the stakes of an inconsistency that might previously have stayed inside a neglected deck.
The gap that follows leaves the company with untidy communications and narrative debt. Different people give different answers to “what’s your story?”, the website reflects a prior leadership era, and sales uses a frame the product team abandoned two years ago. Across a portfolio, these contradictions make the fund’s value-creation approach harder to explain, coordinate, and eventually sell. That turns ownership of narrative into a fund-level operating decision.
The two structural options — what a platform model and an engagement model actually mean
A platform model establishes a shared narrative operating system at the fund level. It contains canonical language, category frames, and story architecture that portfolio companies adapt to their circumstances. The analogy is a fund-level technology or data playbook. Companies share a governing pattern, just as businesses selling different products can share a common technology approach.
The architecture comes before deployment at each company. The fund defines its value-creation thesis in precise language, builds canonical documents, and establishes governance conventions. The FTI outlook describes a comparable pattern in AI, with funds creating repeatable playbooks and infrastructure patterns for deployment across portfolio companies.
An engagement model delivers narrative through projects for each company, often when an event or need calls for one. The work addresses that company’s presenting problem rather than starting from a maintained fund-level system.
A hybrid maintains a lightweight fund-level frame, including a narrative brief, canonical glossary, and value-creation story template, with company engagements working within it. The fund still has to decide what language companies share and who owns it. A hybrid makes the initial structure lighter, leaving the fund responsible for how that structure develops.
What the engagement model costs that never appears on the invoice
Individual engagements can look cheaper per transaction and give the fund room to adapt. Costs that go unseen arise when work meets a company’s needs but has no shared frame to guide it. Each company gets language that fits the problem it faces now, but the fund must later explain those companies together to LPs, co-investors, and buyers.
The same fragmentation develops within companies over time. Event-triggered work can establish a strong narrative at entry without providing a way to update it as strategy changes. Leadership moves on, but the old account persists through sales decks, hiring language, manager habits, and customer promises. Nobody has to execute badly for this to happen. The gap emerges because completing a project and maintaining a system are different jobs.
AI can accelerate that gap. The FTI outlook identifies adoption moving beyond task automation into complex enterprise-wide workflows across portfolio companies. Those workloads draw on the language in their source documents, so fragmented source material can spread inconsistent stories at greater speed and volume. More output is not the same as more agreement. Without a governing language layer, scale can magnify the problem.
At exit, the accumulated debt becomes reconstruction work. Materials from uncoordinated engagements must be reconciled under deal-timeline pressure, potentially too late to shape the buyer’s thesis before the process begins. External audiences also encounter the inconsistencies directly, whether customers hear promises delivery cannot match or buyers find a data room at odds with management’s presentation. LP diligence can expose a further mismatch between company positioning and the fund’s stated approach.
What the platform model requires that most PE firms underestimate
A platform begins with clarity the fund may not yet have formalized. The GP must commit to canonical answers about the problems it solves for portfolio companies, what good looks like at exit, and the fund’s own category. Pleasant ambiguity will not serve as a governing frame. Language precise enough to guide other organizations requires choices about what the value-creation thesis actually means.
Those choices then need an owner over time. M&A, leadership changes, and strategy pivots put narrative infrastructure under stress, just as they strain technical systems. Someone at the fund level must own language governance across the portfolio. Without maintenance, even an expensive platform becomes an elegantly formatted account of how things used to work.
Companies must use the system as well as have the fund’s approval. Portfolio leaders must adapt the system to their context and maintain it under operational pressure. That takes operating partner bandwidth and a mechanism for embedding language into planning, sales enablement, hiring, and management routines. The platform cannot remain a fund-level possession. Its usefulness depends on the people making daily decisions at each company.
The FTI outlook calls for longer-term core infrastructure and capability investments to support scaling AI deployments at portfolio companies. A narrative OS can supply the canonical language layer those deployments inherit. The case for it therefore rests partly on AI ROI as well as better communications. That strengthens the reason to build it, without removing the obligation to maintain it.
The hold-period timing question — when each model fits the actual deal lifecycle
At entry, a fund has the longest runway for shared infrastructure to compound. A platform can establish the value-creation frame and embed it in management onboarding before successive initiatives produce competing accounts of the business. Time favors the investment in maintained foundations. That makes fresh capital and long hold periods important conditions in the choice, rather than treating portfolio size as the only useful guide.
At mid-hold, the test becomes whether narrative changes with strategy. An engagement can respond to a pivot, but its event-triggered structure does not itself govern the language used between projects. The old story can live on in habits, compensation, the words managers use, and promises to customers. A maintained platform addresses that interval. Its role is to keep the operating account aligned while the business changes.
Exit preparation exposes the difference most sharply. A maintained platform makes the exit story an assembly of existing artifacts, while disconnected prior work requires reconstruction. Yet a late-hold asset also offers less time for a new platform investment to compound. An engagement may fit the immediate need without undoing the costs of earlier fragmentation.
Portfolio composition modifies this lifecycle judgment. Large, diverse portfolios offer more scope to spread shared infrastructure costs, while small or highly idiosyncratic portfolios may benefit from the engagement model’s flexibility. Genuine differences in category, stage, or buyer can make a common frame unsuitable. That conclusion needs analysis, however, rather than an assumption that every company is too special to share foundations.
How narrative infrastructure connects to the LP and exit-buyer relationship
LPs need to understand how value was built, how outcomes were tracked, and how lessons from prior investments entered firm-level processes. A repeatable narrative infrastructure gives those questions a structural answer. Consistency becomes evidence of an operating approach. Conversely, portfolio companies that cannot explain their relationship to the fund’s thesis make that approach harder to assess.
The “Radical Transparency” signal is a clear narrative the whole organization understands and can articulate. A management presentation can be rehearsed in isolation. Agreement between that presentation and operational reality is harder to manufacture late in a process, which makes coherence a useful proxy for discipline.
Buyers pay premiums for companies that define and own their category, and a frame used since entry has time to accumulate supporting evidence through customer language, analyst recognition, and competitive framing. A last-minute category story has less history behind it. The FTI outlook also notes that the IPO market in 2026 favors companies using recent market validation and creative deal structures, which require a narrative already working with public-market audiences before the S-1.
At fund level, the same legibility supports fundraising. When the team, LP communications, and portfolio positioning use the same precise language, an LP weighing a new vintage can better understand how the fund invests. It also helps a GP staking capital alongside the firm. External audiences can follow the relationship between the fund’s claims and its companies’ progress.
How should operating partners choose a model and audit messaging across all portfolio companies?
Do the companies share enough category logic, buyer type, or value-creation thesis for a governing narrative frame to apply? New investments with long holds give infrastructure a different return from assets near the end of a hold, where an engagement aimed at the immediate need may fit.
Are portfolio companies running or planning AI workloads at scale, so that shared language governance would help both narrative and AI deployment? Can the fund and company leadership maintain that infrastructure? A platform without an owner is shelfware with better branding. Strong reasons to standardize do not substitute for the operating capacity to keep the standard current.
For funds with coherence and time but limited governance capacity, the practical entry point is a hybrid. A short fund-level brief gives company engagements a frame while the fund works out who will own it. As capacity grows, the platform can formalize canonical documents, company category frames, AI language governance, onboarding materials, and a regular audit cadence.
Storied’s Narrative OS and Storied AI are built for this platform architecture, treating narrative as organizational infrastructure. The fund-level language system supplies the language that company AI, sales enablement, and exit materials draw on. Ongoing audits then serve a distinct purpose. They catch drift before it reaches a data room or LP report, rather than waiting for the next major engagement to reveal it.
The immediate diagnostic is a portfolio-wide narrative audit. Ask five people across three portfolio companies to answer “what’s your company’s story?” and “what’s the fund’s value-creation thesis for this company?”. Compare the answers for consistency. Their alignment reveals the current state of the fund’s narrative infrastructure, regardless of which model appears on the procurement paperwork.