Portfolio Narrative Coherence as a Fund-Level Category Signal
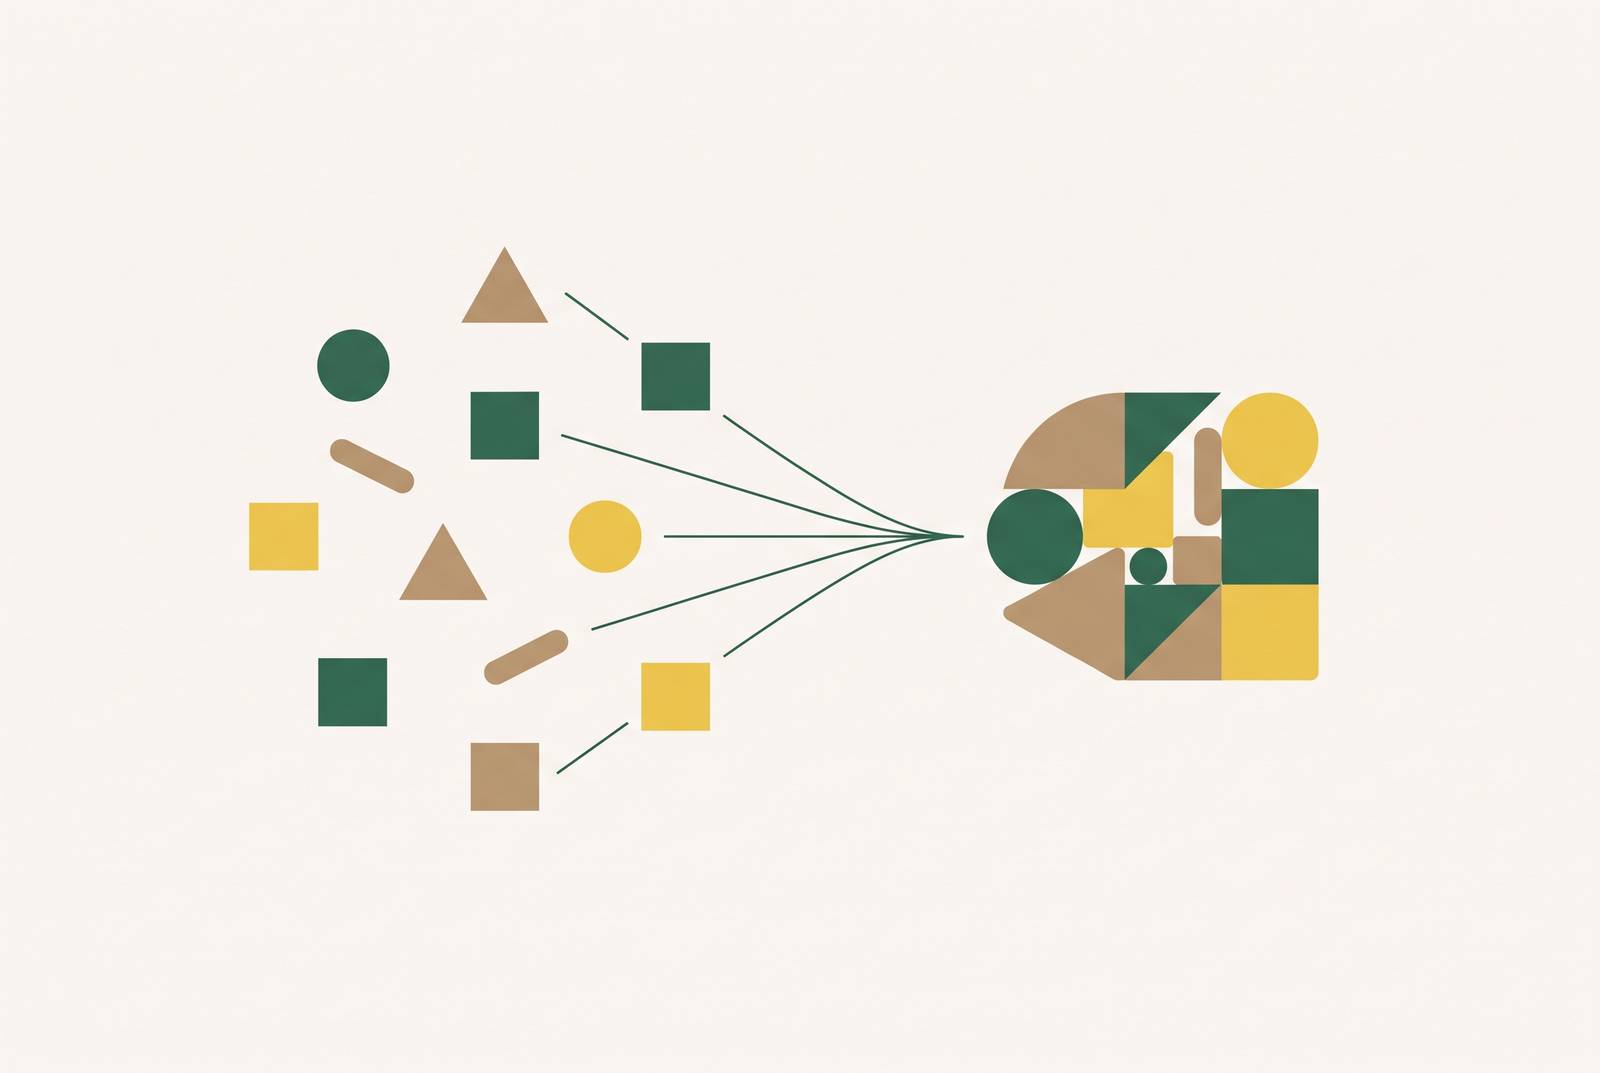
A portfolio-wide narrative audit for VC and private equity firms compares category language, positioning, and decision logic across company documents, team conversations, and customer-facing materials. The aim is to standardize narrative quality while preserving each holding’s distinct language. When that coherence holds across a portfolio, it signals the fund’s thesis discipline and operational value-add.
Why portfolio narrative coherence matters now, not later
The venture market that emerged from the 2022–2023 correction demands more than a collection of promising companies. Wellington's 2026 midyear outlook notes that the top five managers by capital raised captured 73.1% of all venture commitments in Q1 2026, while the top fifteen captured close to nine-tenths. Capital is concentrating around demonstrated performers. For other managers, explaining what they own, why those holdings belong together, and how they can exit has become part of the competitive test.
That test comes from LPs pressed for distributions as well as founders seeking capital. Paper marks offer little comfort when the question is how cash gets back to investors. If the fund describes one market shift while its companies tell unrelated stories about their purpose, the gap raises a question about investment discipline. A good-looking portfolio slide cannot do all the parenting.
Chambers Venture Capital 2026's USA–New York chapter reports that investors ask harder questions about unit economics, profitability, and competitive defensibility, while term sheets that once moved in days now routinely unfold over several weeks. Founders can no longer cover weak metrics with narrative. The reverse applies to funds too. Funds that claim operational value-add need to show how their investment thesis connects to the way their portfolio companies compete.
What narrative infrastructure actually is, and why most funds misread it
Funds often place narrative in the marketing budget because they mistake the output for the system. A pitch deck, website, or investor update expresses a company’s thinking, but none is the thinking itself. Narrative infrastructure is the collection of ideas, stories, and metaphors that shapes what people consider important. It helps them make routine decisions quickly. Under pressure, it also bounds the responses they can imagine and defend.
Language debt builds up much like technical debt. Conflicting definitions may seem tolerable while teams are small, just as a technical shortcut can seem harmless before a system grows. But unresolved differences become costly when sales, product, and leadership must act together. The debt has no balance-sheet line. In a platform or infrastructure company, it may become visible only when go-to-market execution stalls or a sales cycle stretches beyond reason.
This makes language an outside view into internal health. When teams use the same words to mean different things, apparent agreement can conceal incompatible priorities. The Narrative OS framing treats language as an operating layer instead. Its effect appears in what gets funded, stopped, escalated, or protected under pressure. That is a different job from writing a more stirring paragraph after everyone has already decided what to do.
How AI has made narrative fragmentation a fund-level risk, not just a company-level one
AI makes that distinction urgent because it propagates the language a company already runs on. A fragmented system can now produce fluent reports, proposals, customer communications, and investor updates at scale. Output gets easier. Shared meaning does not. Without a governing reference, teams can generate increasingly polished versions of incompatible ideas.
The propensity described as “trendslop” involves LLMs recommending strategies that fit managerial buzzwords with little regard for the company’s specific context. When companies delegate narrative construction without governing language, generic model preferences can displace differentiated positioning. Across a portfolio, that produces a peculiar form of sameness. The companies may sound alike yet show little sign that they share an investment thesis.
A company can lead its category in search rankings while a competitor with less traffic gets repeated LLM citations as buyers do their research. Narrative clarity therefore becomes a distribution variable. When a buyer uses an LLM before entering a formal sales process, the category explanation it retrieves can shape the comparison before a salesperson speaks. Fragmentation now has both an operating cost and a route to market.
Reading narrative coherence as a diligence signal before investment
For a GP, the useful diligence signal is language consistency under stress. Does the customer’s account of the problem match the founder’s? Do sales and product describe the same reason to buy? The underlying explanation must hold when different people describe the business without the deck doing the work for them.
That comparison needs to cover the company’s documents, team conversations, and customer-facing materials. A company may present a compelling new category to investors while its sales team still pitches the old one on calls. The contradiction is a finding about execution. It suggests that the proposed strategy has not yet become a shared operating logic, even if the pitch makes it sound settled. Deferring it to a post-close communications task misclassifies the risk.
The strongest objection is also the necessary limit. Clean language can coexist with poor unit economics, and messy language can coexist with a strong business. Narrative coherence is therefore a co-indicator of organizational health alongside financial diligence and proof of defensibility. It can help more when there is little financial history or when other signals clash. Its diagnostic value comes from exposing whether people are trying to build and sell the same business.
Storied’s approach to narrative diligence addresses that distinction by treating consistency across documents, conversations, and external materials as a structural diagnostic. That is a specific pre-close discipline. It tests how well strategy holds up as it passes through the company, a test that goes beyond whether the company has hired someone who writes well.
How category language, when it holds across a portfolio, compounds into a fund-level thesis signal
Gong named “revenue intelligence” rather than presenting itself as “call recording software,” shifting the conversation from a feature comparison to a strategic initiative. HubSpot invented and named “inbound marketing” and wrote the book on it. These illustrate category-creation mechanisms. The language helped define the market frame within which the product would be understood.
A frame only holds if the company can operate within it. The company’s product roadmap and its choices about pricing, hiring, and partnerships need to fit the position it claims. Otherwise, category creation becomes a marketing department announcing a country that nobody else has agreed to inhabit. The failure starts internally. A sales rep pitching the old category while marketing promotes the new one exposes the break before the market has any reason to believe the claim.
This is why narrative alignment belongs before go-to-market investment. Demand generation can amplify a stable explanation, but it can also amplify confusion. Yet the answer is not to rush every startup into naming a category. Category creation takes time and budget, and the name is the last thing a company earns. A fund’s role is to strengthen the positioning logic so that a category claim, when warranted, has customer proof and internal consistency beneath it.
When two or three companies share a coherent explanation of what is changing in their market and why, outsiders can read the fund’s thesis through its investments. The companies need not use one slogan or claim one category. Their distinct positions can reinforce the same view of market structure. LPs see the relationship, acquirers can begin pattern-matching, and the GP earns recognition for a particular kind of insight.
How can a VC firm standardize narrative quality across its portfolio?
Govern the quality of the language system while preserving each company’s distinct language. GPs can make that work a routine through pre-close diligence, post-close activation, and portfolio governance. Each holding needs canonical documents, definitions its teams share, and a way to keep them consistent when growth or pressure pulls teams apart. Periodic brand audits and pitch coaching do not provide that continuity.
Pre-close, narrative diligence needs to be part of the integrated diligence workstream. Documents and interviews provide evidence of whether the company’s category thesis matches the logic used in selling, building, and prioritizing. Contradictions belong among the findings even when filed in a folder marked “marketing later. This makes narrative a diagnostic before ownership begins. It also connects post-close work to a specific organizational gap.
Post-close activation establishes the canonical references before go-to-market spending begins. These include a governing narrative, a category definition, and a shared vocabulary for the problem the company solves. Does the language change priorities, stop work that no longer fits, and clarify what the team protects under pressure? If it only improves the website, the operating layer is still missing.
Portfolio governance then audits narrative drift on the same cadence as financial reporting. Drift is the accumulated divergence between what a company says externally and what it means internally. It is a leading indicator of misalignment. During rapid scaling, that misalignment can appear as slower decisions, repeated debates, and teams attributing delays to one another. Comparing each holding against its canonical references gives the fund a common discipline while preserving the distinctions that make its companies investable.
AI-assisted work adds a reason to keep those references authoritative. Without them, distributed teams may not know which version governs or which deliverable should serve as the base. Storied’s Narrative OS tackles this operating problem with canonical documents and decision frameworks built to hold up across distributed teams and AI-assisted output.
How portfolio narrative coherence registers with LPs, acquirers, and markets at exit
For LPs, a coherent portfolio makes the investment thesis inspectable. They can assess not only whether the GP selected attractive companies, but whether the choices express an understanding of the market structure connecting them. That is especially useful for a mid-sized fund that cannot compete on check size. Consistent positioning across holdings gives its claimed insight a visible form. It remains an explanation of value, however, separate from cash distributions.
A company with clear, differentiated category language is easier to understand, position in an acquisition announcement, and integrate into a larger strategic story. Category leadership also presents a different valuation argument from feature parity. None of this guarantees a premium. It helps explain why the company deserves consideration as a category asset rather than another product with a comparable feature list.
Fundamentals and entry price still constrain the outcome. Wellington’s outlook notes that even high-quality AI leaders may yield modest multiples at current valuations, depending on the price the allocator pays to get in. Good language cannot negotiate with arithmetic. When fundamentals are comparable, however, category ownership can distinguish the company that becomes the acquisition target from the one used as a comparable. The narrative has to explain a real advantage.
Over time, markets also read the pattern across holdings. A fund whose companies consistently define and win their categories can earn a reputation that attracts better deal flow, stronger co-investors, and higher-quality founders in the next cycle. Each company adds evidence to the fund’s thesis, while the fund’s governing discipline helps the next company make that thesis executable. This is the long-duration advantage of portfolio narrative coherence. A rival can copy the vocabulary. Reproducing the alignment, decisions, and accumulated proof behind it takes much longer.